Is It Too Late to Sell My House?
That depends entirely on the stage the lender has reached. Broadly, the earlier you act, the more options you have.
We cannot promise that a sale will stop repossession action, and you should be careful of anyone who does. What we can do is be straight with you about whether a sale is realistic in your timescale.
- Arrears have just started: there is usually the most room to agree a plan with the lender, or to sell on the open market.
- Lender action has begun: a sale is still possible, but the timescale starts to matter and the lender should be kept informed.
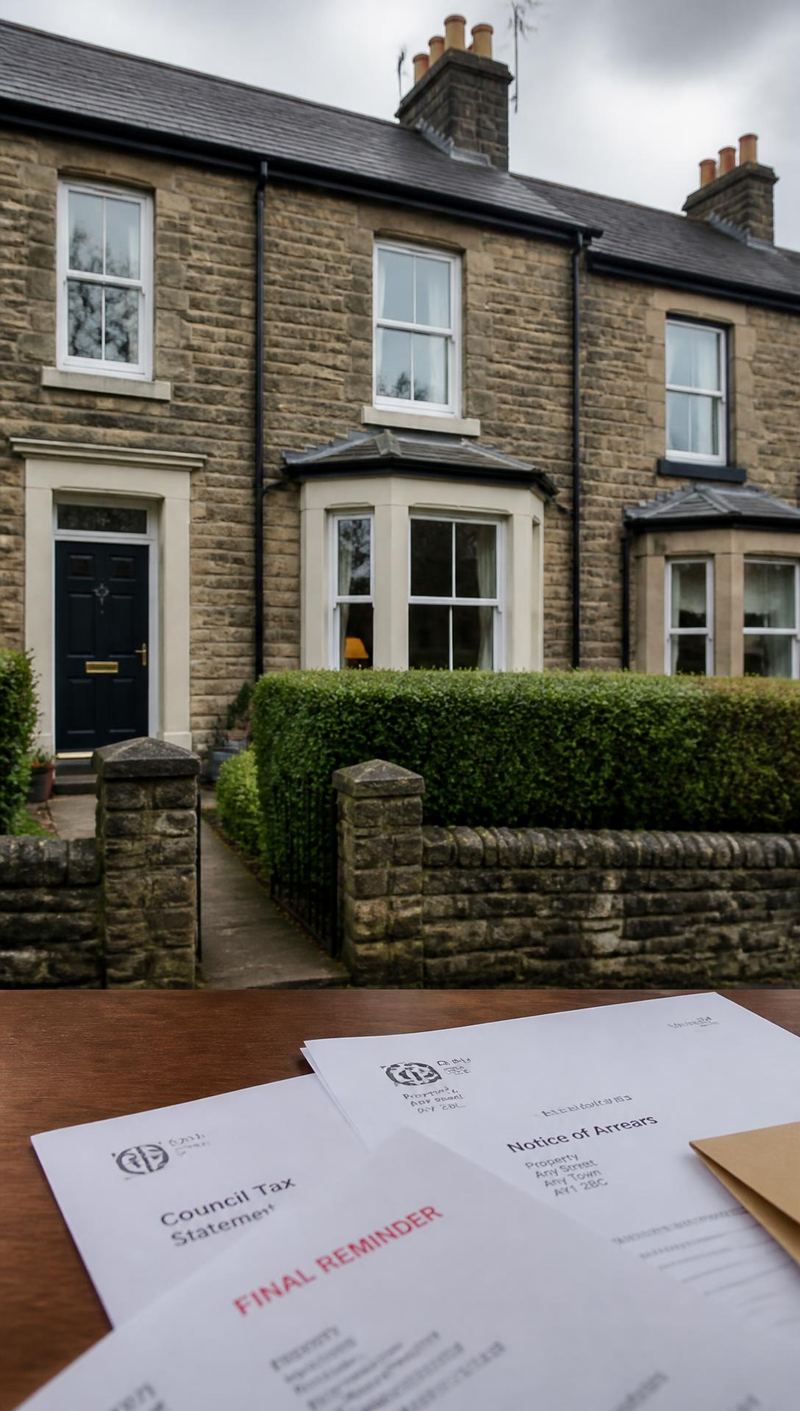
- Court papers have been received: a genuine, evidenced sale in progress is something lenders and courts will often take into account, but nothing is guaranteed.
- Repossession is advanced: options narrow considerably, and independent advice becomes essential before you do anything.
What Happens to the Mortgage and Any Shortfall?
When a property is sold, the mortgage and any secured loans are repaid from the proceeds by your solicitor. If there is money left over, it is yours.
If the property is worth less than the debt secured on it, that is a shortfall, and your lender must consent to the sale. Tell us the figures early and we will be honest about whether a sale can work, rather than letting you spend weeks on something that cannot complete.